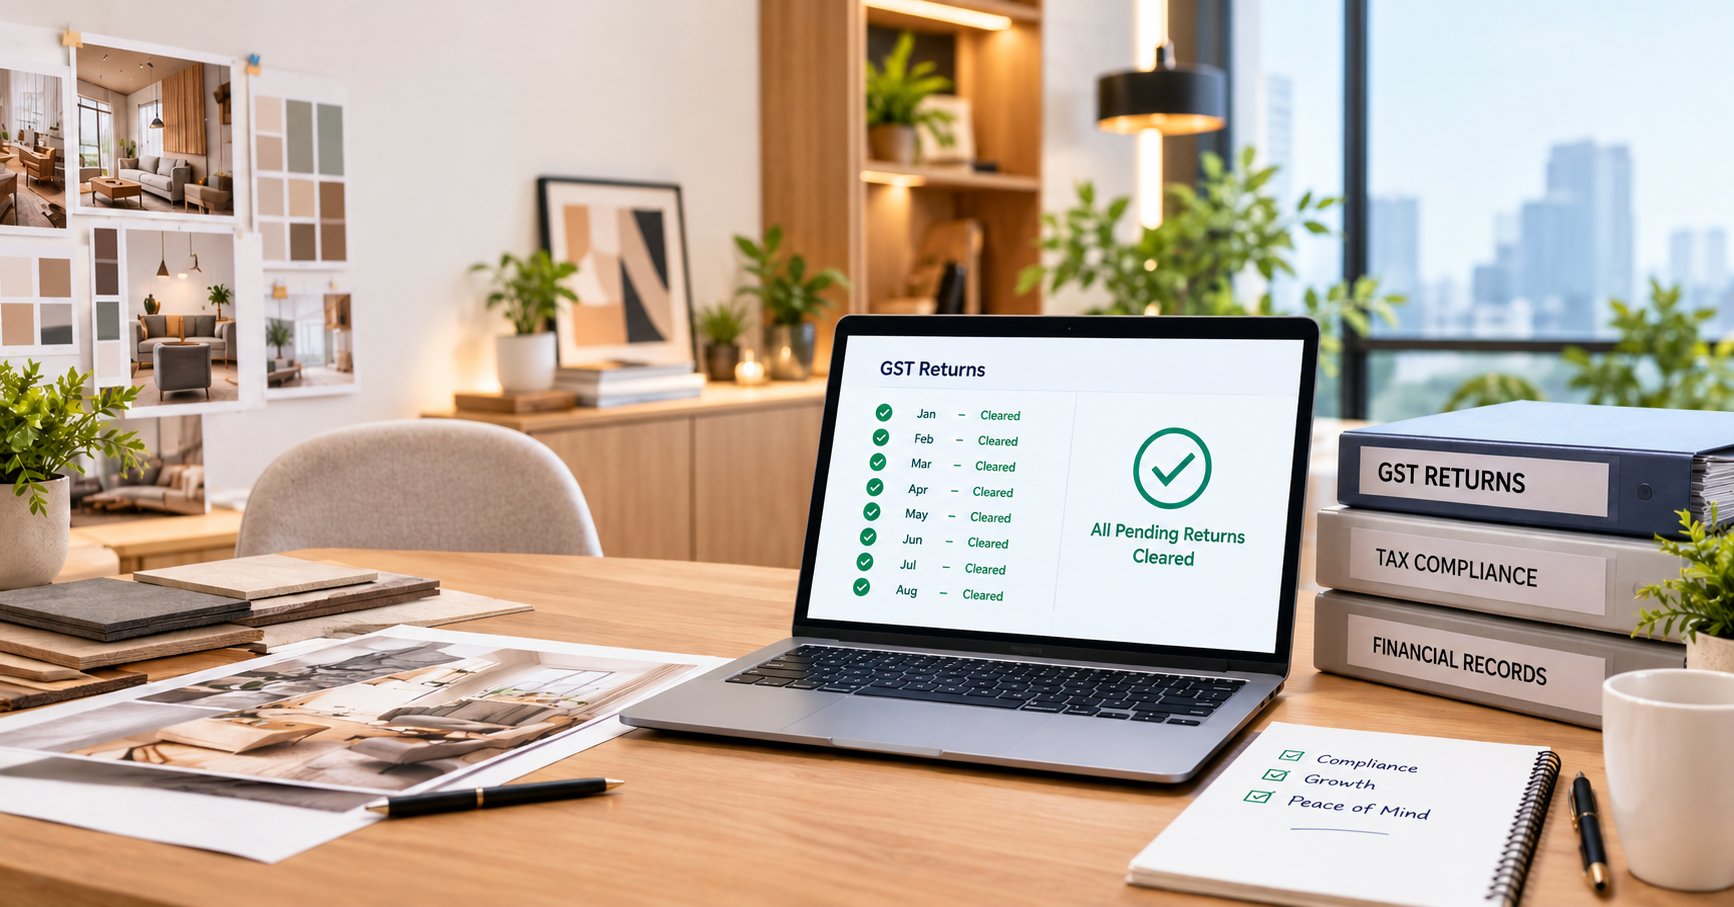
How a Whitefield Interior Design Firm Cleared Eight Months of Pending GST Returns
Mambiz Solutions helped a Whitefield interior design firm clear eight months of pending GST returns, resolve compliance issues, and recover client payments.
For businesses registered under GST, two returns play a critical role in maintaining a clean compliance record: GSTR-1 and GSTR-3B. Although both returns relate to your business transactions and are filed regularly, they serve different purposes. Any significant difference between the information reported in these returns can attract scrutiny and may result in a GST notice.
This guide explains the key differences between GSTR-1 and GSTR-3B, their filing deadlines, common mismatches that may trigger notices, and practical ways to maintain accurate GST compliance.
GSTR-1 is a return that reports your outward supplies, or the sales made by your business. It provides detailed, invoice-level information about your transactions, including the customer, goods or services supplied, and applicable tax.
A typical GSTR-1 includes:
B2B invoices reported with the buyer’s GSTIN
B2C sales reported in applicable large-value or summary formats
Exports and supplies to SEZs
Credit notes and debit notes
Amendments to previously reported invoices
HSN/SAC-wise summary of supplies
Advances received and adjusted
GSTR-1 is a reporting return and does not involve direct payment of tax. However, the information submitted has an important impact on your customers because invoice details reported in GSTR-1 flow into their GSTR-2B. Incorrect or delayed reporting can therefore affect their ability to claim input tax credit.
GSTR-3B is a summary GST return through which tax liability is reported and paid. Unlike GSTR-1, it does not contain invoice-level details. Instead, it consolidates the relevant figures for the tax period.
GSTR-3B generally captures:
Total outward taxable, zero-rated, nil-rated and exempt supplies
Supplies subject to reverse charge
Inter-state supplies to specified categories of recipients
Eligible ITC, along with reversed or ineligible ITC
Exempt, nil-rated and non-GST inward supplies
Interest and applicable late fees
Tax payment through electronic cash and credit ledgers
Simply put, GSTR-1 reports what you sold, while GSTR-3B reports your tax liability, ITC, and tax payment.
| Parameter | GSTR-1 | GSTR-3B |
|---|---|---|
| Purpose | Detailed reporting of outward supplies | Summary of sales, ITC, and tax payment |
| Level of detail | Invoice-wise | Consolidated figures |
| Tax payment | No | Yes |
| ITC reporting | No | Yes |
| Impact on others | Feeds information into the buyer’s GSTR-2B | Determines tax payment and ITC utilisation |
| Frequency | Monthly or quarterly under QRMP | Monthly or quarterly under QRMP |
| Late fee exposure | Applicable under GST law | Applicable, with interest on delayed tax payment |
The key point is simple: GSTR-1 and GSTR-3B should present a consistent picture of your business transactions.
The applicable due date depends on whether you file returns monthly or under the Quarterly Return Monthly Payment (QRMP) scheme.
GSTR-1: 11th of the following month
GSTR-3B: 20th of the following month
For example, for the September 2026 tax period, GSTR-1 was due on 11 October 2026, while GSTR-3B was due on 20 October 2026.
Under the QRMP scheme:
GSTR-1: 13th of the month following the quarter, with the option of using the Invoice Furnishing Facility (IFF) for the first two months
GSTR-3B: 22nd or 24th of the month following the quarter, depending on the state
PMT-06: 25th of the month for the first two months of the quarter
For Karnataka, quarterly GSTR-3B is filed by the 22nd. Therefore, a Bengaluru-based QRMP taxpayer filing for the July–September quarter would generally file GSTR-1 by 13 October and GSTR-3B by 22 October.
GST authorities may extend filing deadlines for specific tax periods or regions through official notifications. Therefore, businesses should verify the latest due dates on the GST portal or with a qualified tax professional instead of relying solely on standard deadlines.
Missing GST filing deadlines can result in additional financial costs.
Late fee: A per-day late fee may apply to delayed returns, with applicable concessions and limits depending on the return and circumstances.
Interest on delayed tax payment: Interest may apply to unpaid tax from the applicable due date.
Interest on wrongly availed ITC: Higher interest may apply where ITC is wrongly claimed and utilised.
Even when there is no tax liability, applicable returns must still be filed. Continuous non-filing can create compliance issues and may contribute to cancellation proceedings against a GST registration.
The GST compliance system uses automated data comparisons. Information reported in GSTR-1 and GSTR-3B can be compared, along with supplier and recipient data. Significant differences may attract attention from the tax authorities.
Some common mismatches include:
This is one of the most important mismatches. For example, if GSTR-1 reports ₹50 lakh of taxable sales while GSTR-3B reports only ₹40 lakh, the difference may be viewed as under-reporting of turnover.
Common reasons include:
Invoices reported in GSTR-1 but omitted from GSTR-3B
Credit notes adjusted differently
Timing differences between reporting periods
Data-entry or reconciliation errors
Even when taxable turnover appears consistent, differences in tax liability can attract scrutiny.
Possible causes include:
Incorrect GST rate
Incorrect place-of-supply treatment
IGST versus CGST/SGST classification errors
Manual data-entry mistakes
GSTR-2B provides an auto-drafted view of eligible input tax credit based on supplier filings. If the ITC claimed in GSTR-3B exceeds the available credit reflected in GSTR-2B, the difference may require clarification or reversal.
Businesses should regularly reconcile their purchase records and GSTR-2B before claiming ITC.
Reverse-charge transactions need to be reported correctly in the applicable sections of GSTR-3B. Differences between RCM tax liability, payment, and corresponding ITC can result in reconciliation issues.
For the November 2025 tax period onward, certain auto-populated inter-state supply details in Table 3.2 of GSTR-3B are locked and cannot be directly edited. These figures are sourced from GSTR-1 or GSTR-1A.
If the underlying figure is incorrect, the correction needs to be addressed through the applicable GSTR-1A process before filing GSTR-3B. This makes accurate GSTR-1 reporting even more important.
Delayed or missed GSTR-1 filing can prevent customers from seeing their invoices in GSTR-2B. This can affect their ITC claims and may result in follow-ups from customers as well as compliance concerns.
Advances, invoice amendments, and credit notes can easily be missed during reconciliation. When such transactions appear in one return but not the other, differences may arise.
Understanding the type of notice received can help you determine the appropriate response.
GSTR-3A: Reminder notice for non-filing of a return.
ASMT-10: Scrutiny notice issued when discrepancies are identified during return examination.
DRC-01B: Intimation relating to differences between liability reported in GSTR-1 and tax paid through GSTR-3B.
DRC-01: Show cause notice proposing tax, interest, and applicable penalty under relevant provisions.
ITC mismatch notice: May arise where the ITC claimed does not align with available credit or other GST records.
Ignoring a GST notice can make the situation more complicated. Unanswered notices may lead to further proceedings, demand orders, and other enforcement actions.
From 1 July 2025, certain GST returns, including GSTR-1 and GSTR-3B, cannot be filed on the GST portal once three years have passed from their original due date.
Businesses with pending returns should therefore review and clear outstanding filings as soon as possible to avoid losing the ability to file them through the portal.
Preventive compliance is much easier than resolving a notice. Businesses can adopt the following practices:
Complete and verify your outward-supply reporting before filing GSTR-3B to maintain consistency between the two returns.
Compare your books, GSTR-1, and GSTR-3B before filing. Any difference should be identified and properly explained.
Regularly compare purchase records with GSTR-2B and follow up with suppliers when invoices are missing or incorrectly reported.
Avoid leaving invoice entries until the end of the month. Timely accounting reduces the possibility of omissions and data-entry errors.
Ensure credit notes, debit notes, and invoice amendments are accurately reflected in the relevant GST records.
Before filing the annual return, reconcile your books, GSTR-1, GSTR-3B and GSTR-2B to identify unresolved differences.
Set reminders before each filing deadline so that returns are not left until the last day.
Maintain invoices, e-way bills, e-invoice records, bank statements and reconciliation statements. These documents can be valuable when responding to a GST query or notice.
If you receive a GST notice, take the following steps:
Read the notice carefully and identify the notice type, tax period, amount involved, and response deadline.
Do not ignore it. Review the issue calmly and determine what caused the discrepancy.
Reconcile the figures with your books, GST returns, and supporting records.
Pay admitted liability where applicable, along with the required interest.
Submit your response within the prescribed deadline with a clear explanation and relevant documents.
Consult a GST professional if the issue involves significant tax exposure, ITC disputes or a show cause notice.
GSTR-1 and GSTR-3B are closely connected parts of your GST compliance process. GSTR-1 communicates your outward-supply details, while GSTR-3B reports your tax liability, ITC, and payment.
Keeping both returns aligned, reconciling your records regularly, and matching ITC with GSTR-2B can significantly reduce the risk of discrepancies, penalties, interest, and unnecessary GST notices.
At Mambiz Solutions, we support businesses with monthly and quarterly GSTR-1 and GSTR-3B filing, GSTR-2B reconciliation, GST notice responses, and annual return preparation across Karnataka and India.
Avoid the stress of mismatches and missed deadlines. Contact Mambiz Solutions for a GST compliance consultation and let our experts help keep your GST returns accurate and compliant.
👉 https://mambizsolutions.com/
Mambiz Solutions helped a Whitefield interior design firm clear eight months of pending GST returns, resolve compliance issues, and recover client payments.
Karnataka GST thresholds: ₹40L for goods and ₹20L for services/mixed supplies. Timely registration helps avoid penalties and tax liabilities.
Running a business in India means dealing with GST sooner or later. Many new owners find it confusing. Who has to register? What d…